Commercial property
Protect the buildings, equipment and inventory your business depends on, and the income you'd lose if a covered event shut you down.
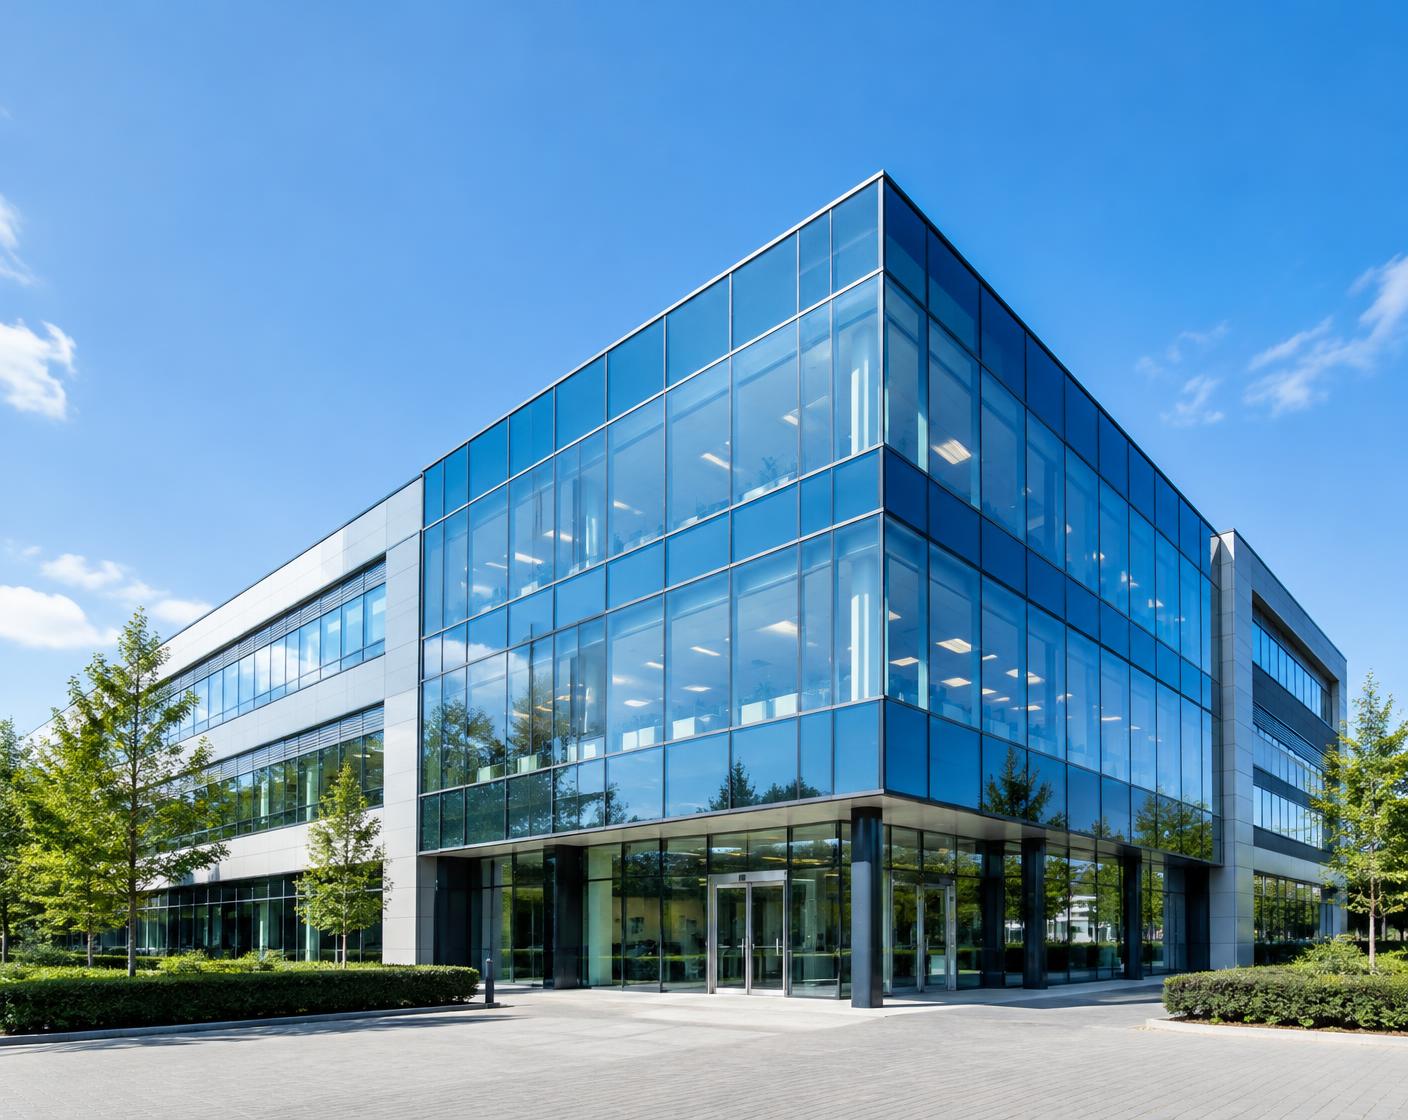
Commercial property insurance covers physical assets against fire, theft, wind, hail and other covered perils. We help you set accurate values so you're not underinsured when it matters.
What's covered
Buildings
Covers structures you own, including permanent fixtures and improvements.
Business personal property
Covers furniture, equipment, inventory and supplies.
Business income
Replaces lost income and pays continuing expenses after a covered loss.
Equipment breakdown
Covers mechanical and electrical failures of systems like HVAC and refrigeration.
Ordinance or law
Pays the extra cost to rebuild to current building codes.
Loss of rents
Protects landlords from lost rental income while a property is repaired.
Who it's for
- Building owners
- Landlords & investors
- Retailers
- Offices
- Manufacturers
- Warehouses
Property types we insure
Real estate programs for owners, investors and managers.
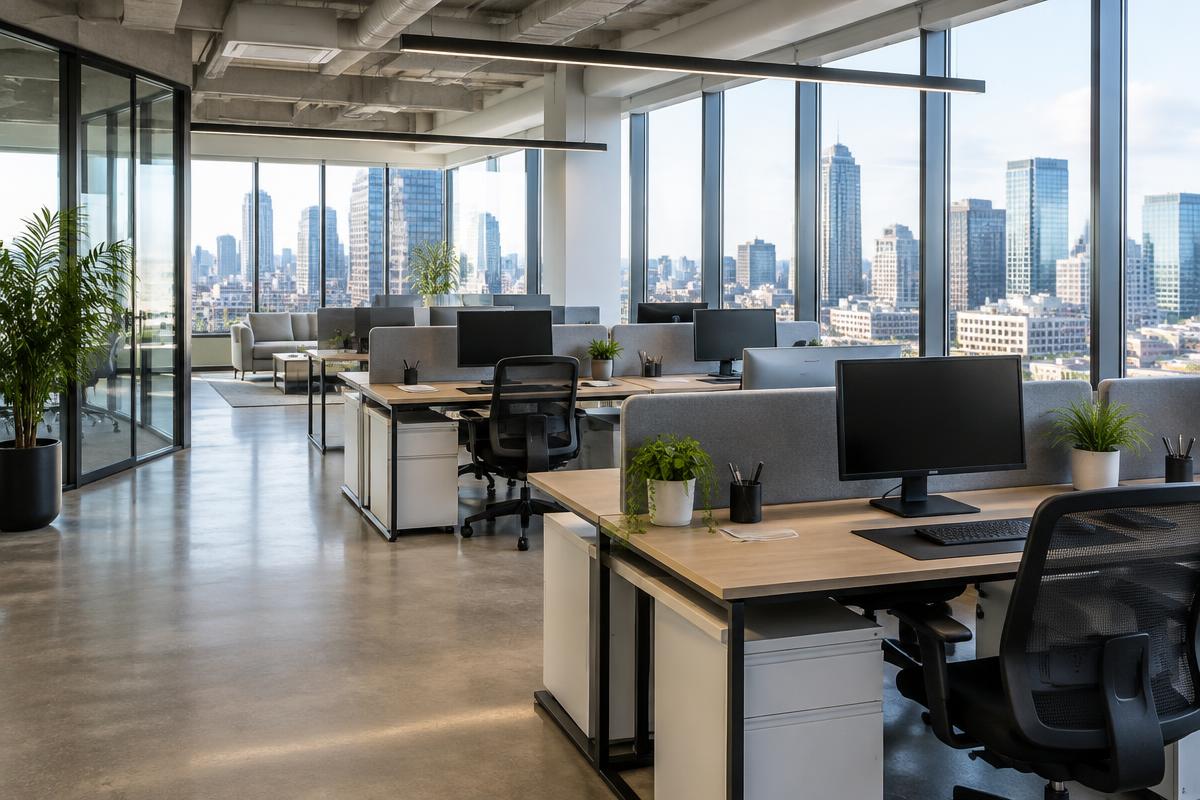
Commercial office
Property damage, premises liability, business interruption and tenant-related coverage, tailored to local risks.
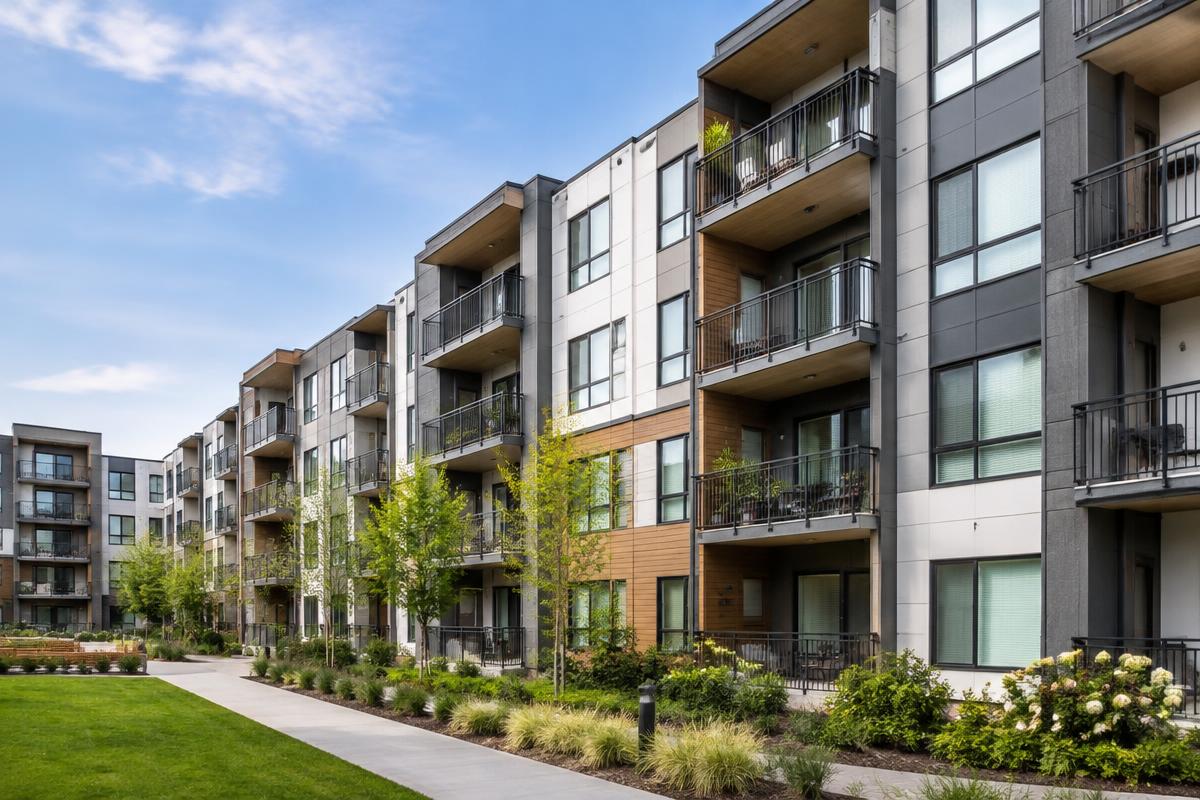
Multi-family properties
Resident injury liability, building coverage and loss of income, including Section 8, student and senior living, condos, HOAs and third-party managed properties.
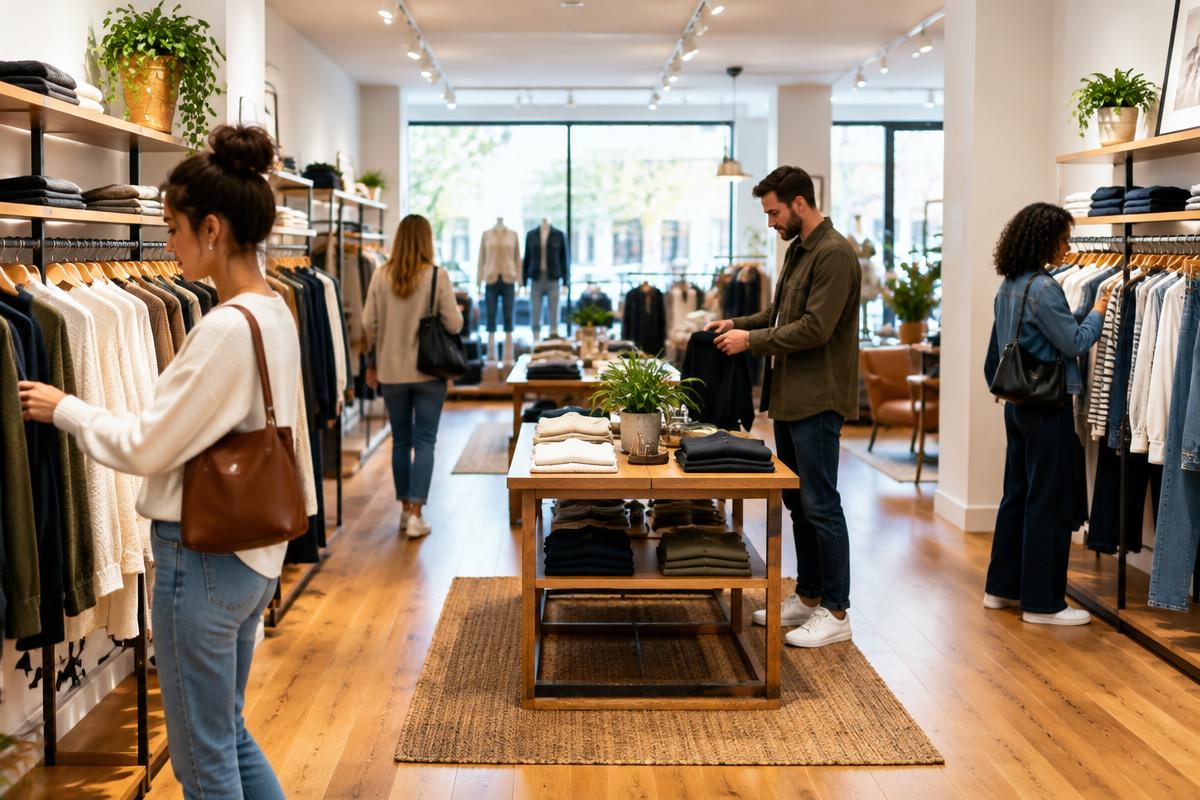
Retail & mixed use
Property, liability and loss of income, plus endorsements for utility failures and the operational risks of high customer traffic.
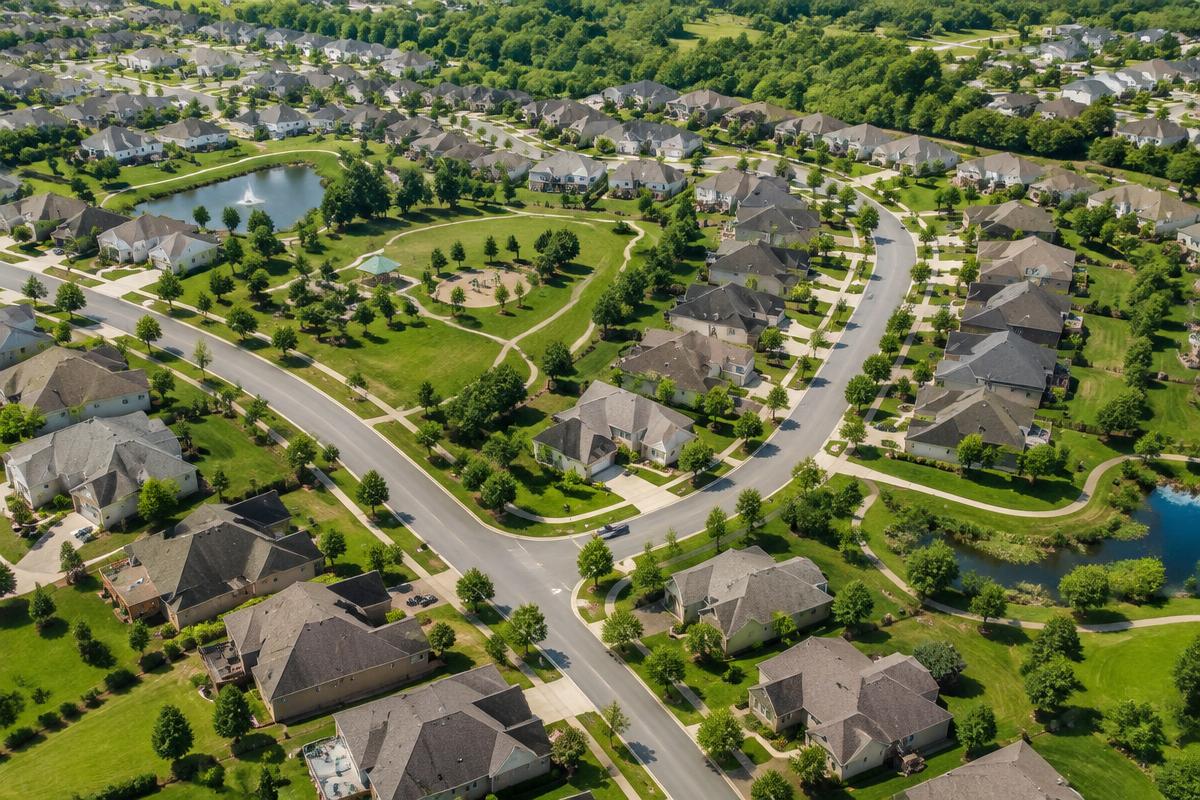
Single-family communities
Liability for common areas, coverage for community-owned structures, and protection for HOAs, managers and community events.
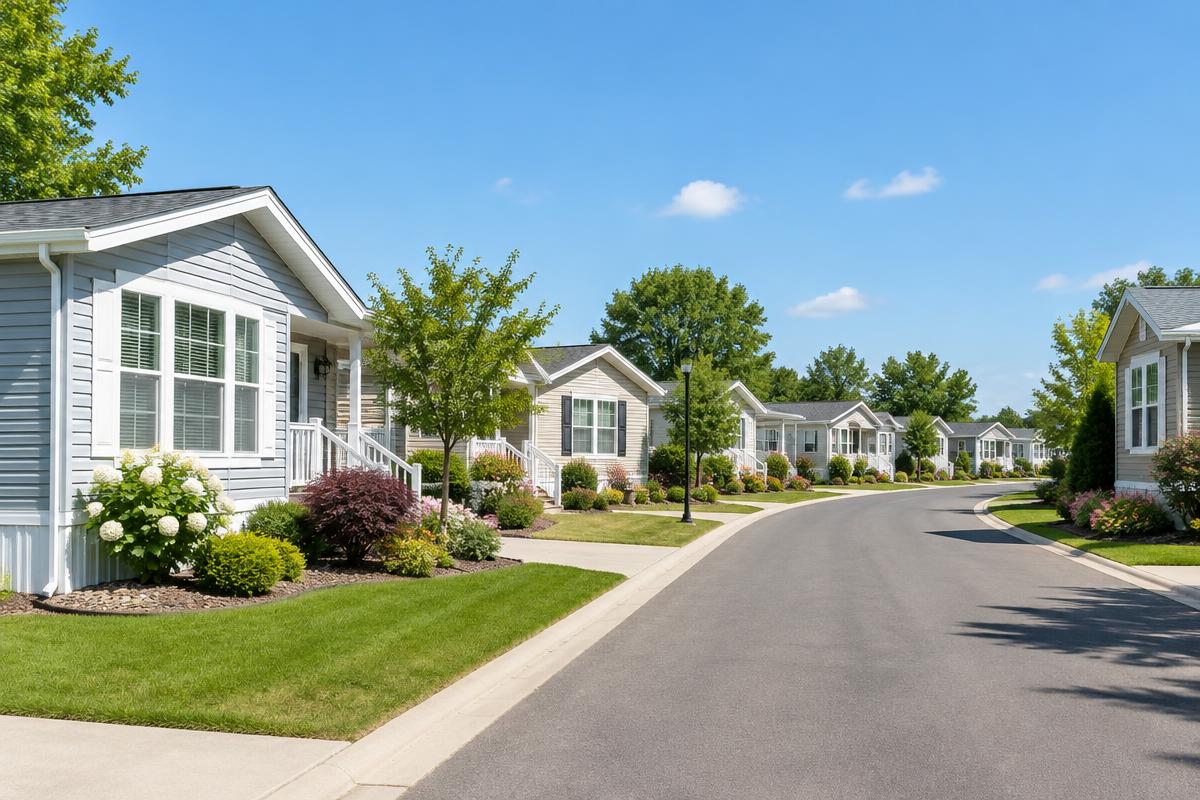
Manufactured housing
Property and liability coverage for manufactured and mobile homes and their communities, including moving and setup.
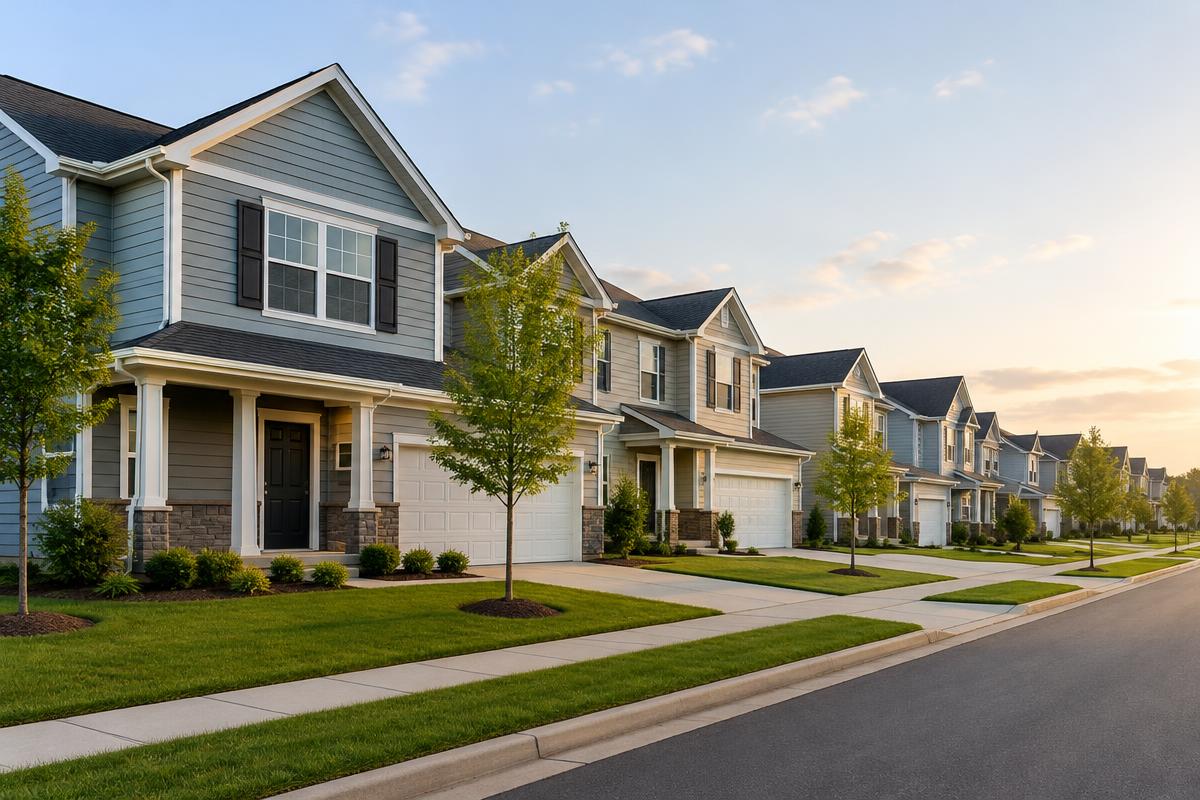
Single-family rental portfolios
Bundled property, liability, loss of rental income and renovation coverage for investors managing multiple single-family homes.
Common questions
Should I insure at replacement cost or actual cash value?
Replacement cost pays to rebuild or replace without deducting depreciation, so it usually provides much better protection. We'll compare both for your property.
Is flood covered under commercial property?
Typically not. Flood requires a separate policy, which we can place alongside your property coverage.
What is coinsurance?
Many policies require you to insure a property to a percentage of its value. Underinsure it and claim payments are reduced, so accurate valuations matter.
Have questions about your policy?
Talk to a licensed agent who knows your file. We'll review your coverage, answer questions and find savings where we can.