Long-term disability
Long-term disability protects an employee's income when a serious illness or injury keeps them from working for months or years.
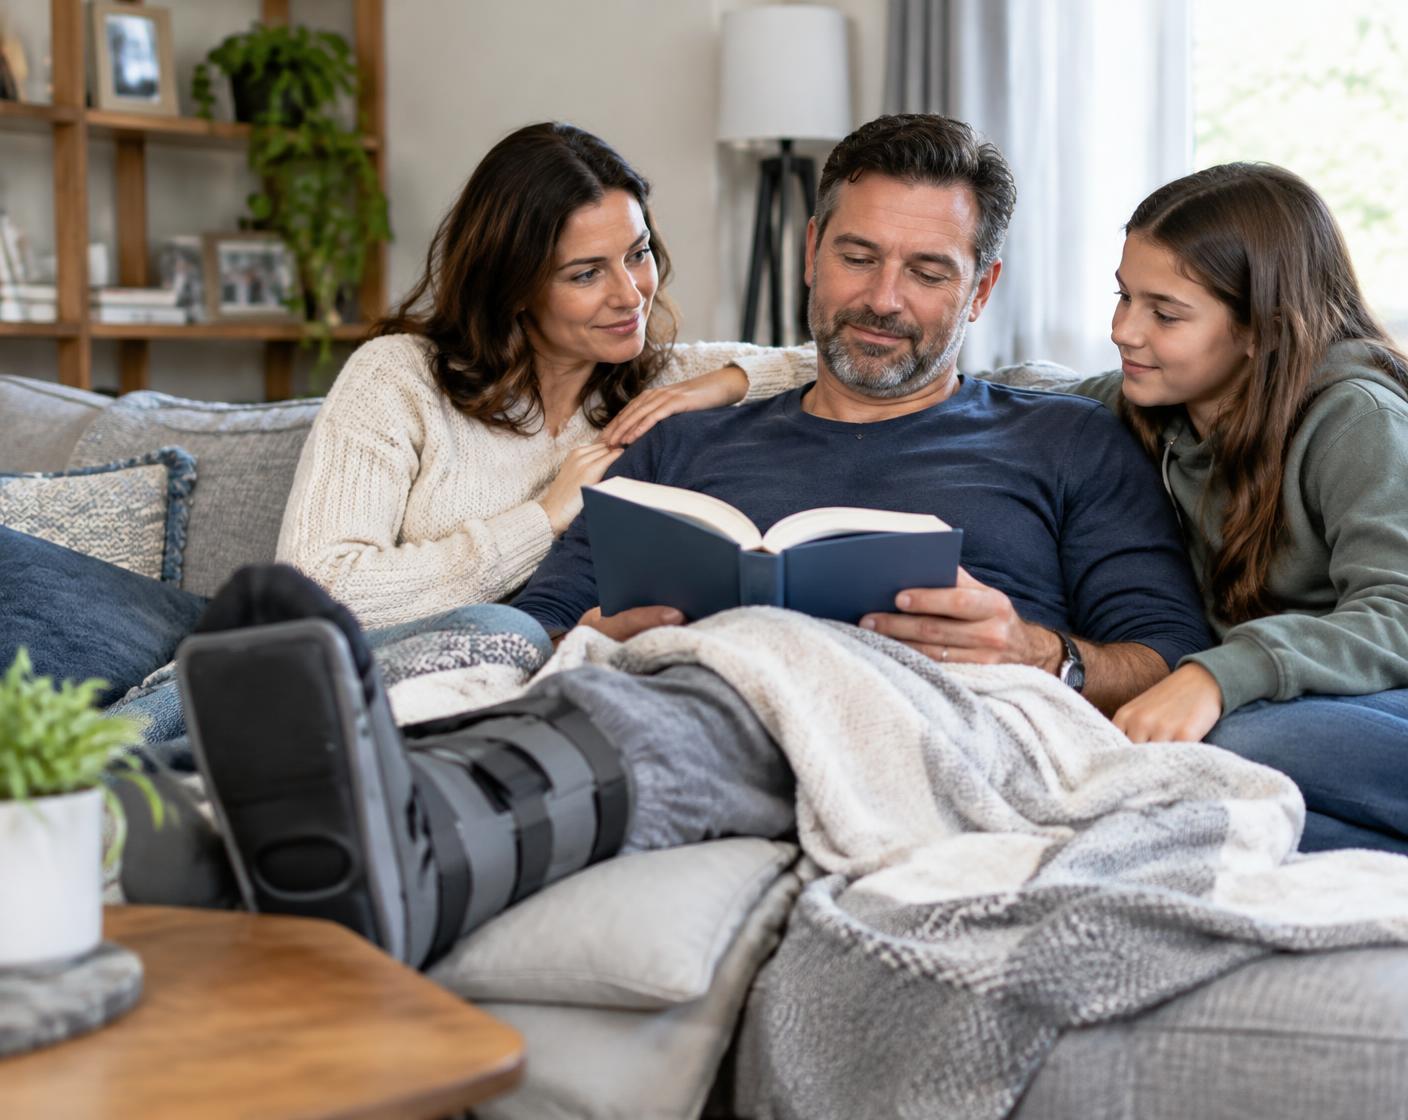
An employee's ability to earn is often their most valuable asset. Group long-term disability protects it at a fraction of the cost of individual coverage.
What's covered
Extended income replacement
Commonly pays around 60% of monthly earnings.
Long benefit periods
Benefits can continue for years, sometimes to retirement age.
Coordinates with short-term
Typically begins after a 90 or 180 day waiting period, when short-term disability ends.
Return-to-work support
Rehabilitation and partial benefits help employees transition back to work.
Definition of disability
We explain own-occupation and any-occupation definitions so you know what you're buying.
Employer or voluntary
Offer it as a paid benefit or on an employee-paid basis.
Who it's for
- Professional firms
- Employers with skilled workforces
- Businesses building competitive benefits
Common questions
Why offer long-term disability?
Long disabilities are more common than many people realize, and few employees have savings to cover months without income.
Are benefits taxable?
It depends on who pays the premium. If the employer pays, benefits are generally taxable to the employee. We'll explain how each option works.
What is the elimination period?
The waiting time before benefits begin, often 90 days. It's usually set to line up with the end of short-term disability.
Have questions about your policy?
Talk to a licensed agent who knows your file. We'll review your coverage, answer questions and find savings where we can.